The original Suica card came out in 2001, back when smart phones as we know them today didn’t exist. Later, the ability to have a Suica card automatically recharge from a linked View Card was introduced, and with that advancement, the need to charge at a ticket machine was removed from the equation. Most people used cash to charge at ticket machines, so the need to use cash was also removed.
A few years later, Mobile Suica was introduced, which allowed members to use Suica on their phones, without the need to carry a card. By this time, many stores around the neighborhood, and all stores in the train stations accepted Suica as a payment method. Mobile Suica could be charged on your phone (via credit card), and you could tap your phone to pay as well.
Suica competed with Edy, QuickPay and iD – the latter two of which were at the time always linked to credit cards, and so post-pay methods. Suica, Edy, Waon, and Nanaco on the other hand, are pre-paid. In fact, they don’t just act like prepaid cards, the balance is actually stored on the card.
This means that Suica (including mobile Suica) has some inherent advantages over other schemes.
1. You don’t need internet (f.e. mobile coverage) to pay. You have full payment functionality without needing internet.
2. You need internet to charge Mobile Suica on your phone via a credit card – both both your phone and cards (as well as smart watches, etc). can be charged at ATMs, convenience store counters, and some ticket machines via cash.
3. You don’t need to create an account, show your ID, or register any credit card or bank account in order to create a normal, unregistered Suica card, or basic Mobile Suica account. This means anyway can always create and use Suica. This includes tourists and other foreigners, people not eligible for credit cards, etc. Suica can be as anonymous as cash.
4. Suica still works perfectly fine in card form, which makes it easy to have multiple cards. Tellingly, you can add up to 20 cards per person to the JRE Point system.
Each Suica card (Physical or mobile) can hold up to 20,000 yen, and the balance is guaranteed for 10 years. Suica is accepted at most places, is compact, is run by a very large company not likely to go bankrupt and disappear. It can take advantage of the internet (i.e. mobile charging and online purchases via Suica Pocket), while working just fine with no internet access.
It can be used 100% anonymously, but also supports registering your name and phone number for peace of mind if you prefer. This means you can combine the privacy and anonymity benefits of cash with the convenience of cashless payments. Or, you can set up automatic charging from a credit card, register your cards to protect against theft, and with JRE Point service, you can even be paid for the privilege.
What’s more, while most modern smart phones have a limit of virtual 4 cards per phone, there is no limit to the number of physical cards you can purchase. You can safely store your money in Suica, and buy as many cards as you like.
Suica is not the perfect payment method, though. It was created to handle transportation payments. While it works great for shopping at the grocery store, convenience stores, and vending machines, the 20,000 limit per card can prevent you from making large purchases.
This limit is necessary, though, because again, the balance is stored on the card. Suica uses a Sony technology called Felica, and it’s not impossible that a card could be hacked. Granted, it would require meticulous dissection by someone with technical skill and expensive equipment. I mean if you are an expert in electronic hardware and encryption and have access to an electron microscope, anything’s possible, I suppose.
In order to make sure hacking the cards is not worth anyone’s time and effort, the value is capped at 20,000 yen per card, which is still plenty enough for everyday shopping, and taking public transportation.
Another problem with Suica is that not all foreign phones have the Felica hardware, which means that foreign tourists often couldn’t use Suica. (Previously, another hurdle was that only a few approved Japanese credit cards could be used to charge Mobile Suica, though apparently that has been improved with integration with Apple Pay and Google Pay).
Also, there have been times during the semiconductor crunch when new Suica cards couldn’t be purchased. This was a temporary situation, but still not ideal.
Recently, though, there have been two new contenders:
1. Visa Touch and its ilk
Honestly, I am not impressed.
Visa Touch can’t do anything iD or QuickPay can do. The sole advantage is that Touch can be used overseas in many countries. Well, so can the CHIP&PIN payments. I can handle inserting a credit card while I am overseas.
Too little, too late. Why should I want to use Visa Touch over iD or QuickPay? They are supported by fewer merchants in Japan, and typically cost more (which results in lower point ratios, cashback etc.)
Still, some people have gone this route. Even more amazingly, some train companies have started accepting “touch” cards for train fare. Normally the fees Visa and the others charge would be high enough to make this uneconomical, so I can only imagine they are offering low rates for now. Still, if one day iD, Suica, and the others die out – well then I am sure they wouldn’t hesitate to raise their rates!
Compared with Suica itself, Visa Touch, iD, and QuickPay also offer higher payment ceilings, since they all are postpaid and contact the bank (hence taking longer to process than Suica or Nanaco).
2. PayPay and other QR Code Payment systems (f.e. Yucho Pay, au Pay, etc).
These systems have come into being recently, and only really work because of the ubiquity of smart phones with always on internet.
These are also prepaid like Suica, but instead of using fancy Felica or NFC hardware, they just use QR codes on the screen or store sign. What this means is that a normal phone camera and screen are enough to work properly.
The QR Code can change every few seconds for security – so showing the right code at the right time is proof that you are the owner of the account. These work primarily online, which means that the smart phones don’t need to hold much in the way of secret data. The servers can check the account holder’s balance and authorize transactions much like credit card companies do for online transactions.
Since these only work on smart phones, you need a smart phone or similar device. There is no PayPay QR code card. Such a device would have to have a camera, screen, and internet – which is difficult and expensive in a credit card form factor.
That means that in practice, anonymous payments via PayPay and similar schemes are difficult. They will let you sign up without providing ID, and you can charge using cash – but the limits will be low until you verify your ID with them.
This may be a good thing too, since while possession of a Suica card is enough to prove ownership, what do you do if you had a large balance on your unregistered paypay account and you acidentally reset your phone or deleted the app?
Still, the QR code payment schemes do have some advantages.
One advantage is the lack of need for any specific terminal hardware. A small mom & pop shop can simply print out a QR code and slap it on a sign after registering for a merchant account. The startup fees are close to zero. Compare this with getting a terminal that can process Suica cards.
PayPay is especially advantageous for merchants compared traditional credit cards. Merchants usually end up having to pay several percent of gross proceeds to credit card processors. (Where did you think your points and cashback were coming from?) While this is lower for Suica, it’s apparently even lower for PayPay and similar.
They don’t need to issue costly IC cards or manage special terminals. Even charging by cash is handled by ATMs, so no charging terminals to maintain either. Then there is no processor-bank-card split – basically, it’s all one company if you use PayPay. It’s easy to imagine that PayPay and similar services have lower running costs than legacy credit card companies.
Also, if you want to send money to a friend, you can easily do that with PayPay. That’s something that isn’t possible with Suica, or with credit cards in general.
QR Code payment systems also naturally work online, as issuing a special temporary URL to authorize your balance isn’t much of a stretch when you need to be online anyway. Mobile Suica can be made to work online as well, but needs to go through the app (since the app needs to deduct the balance from the hardware on your phone!), and it is not widely accepted.
For me: I distinctly dislike needing to take my phone from my pocket, unlock the screen, open an app, and display a QR code every time I make a purchase at 7-11 or so. I value the ability to charge with cash, keep multiple cards, and work offline. I like the ability to leave my phone at home and go for a run with a Suica card in my pocket in case I need to buy a drink.
However for peer to peer payments and larger purchases, Suica doesn’t cut it. Likewise, there are some merchants that are otherwise “cash only” who accept PayPay because it’s easy and low cost to do so.
In those situations, paying by credit card (via Chip & Pin, iD, or “Touch”) or bringing cash are still the main methods available. After all, BitCoin has failed miserably as a currency.
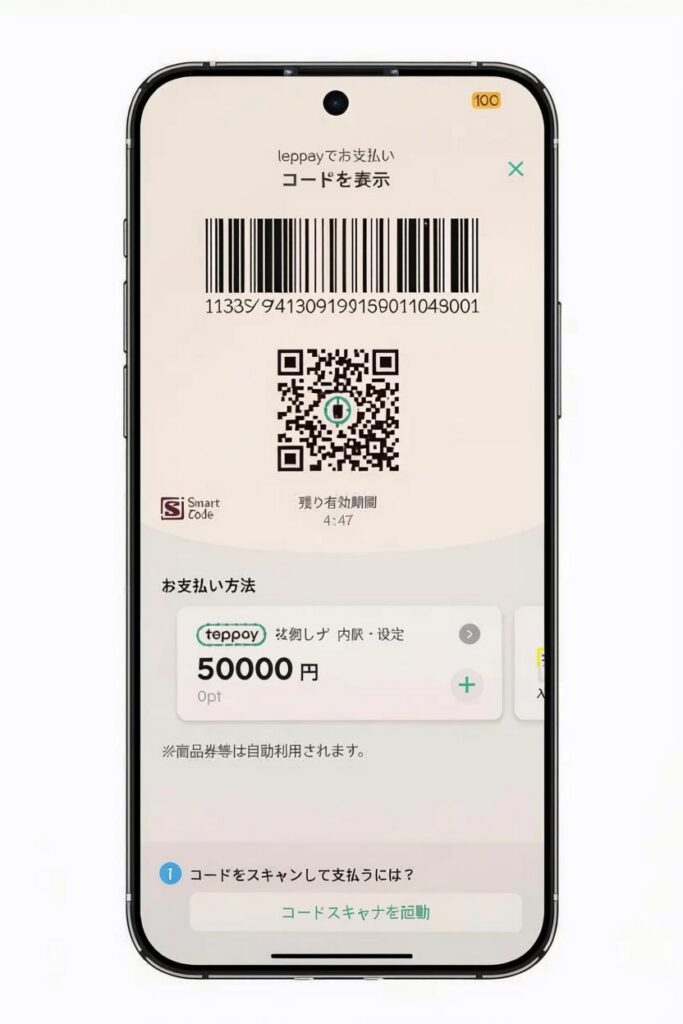
Japan Rail has recognized this, though, and… on October 20th, 2026, they are releasing the oqn QR Code Payment system, Teppay. One can only assume this stands for “Tetsudo Payment”.
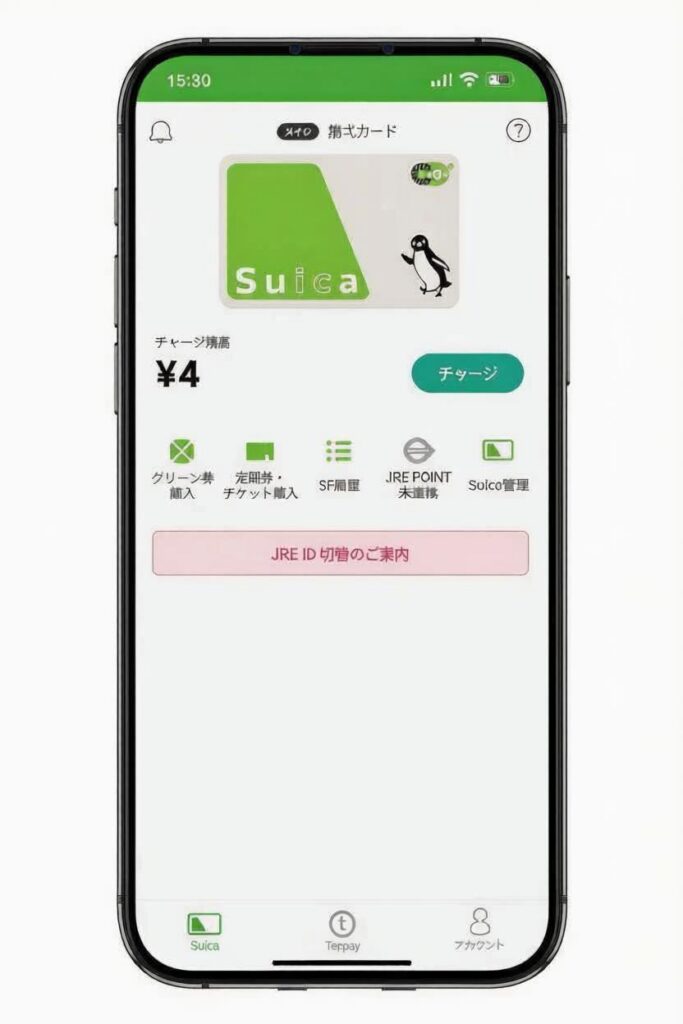
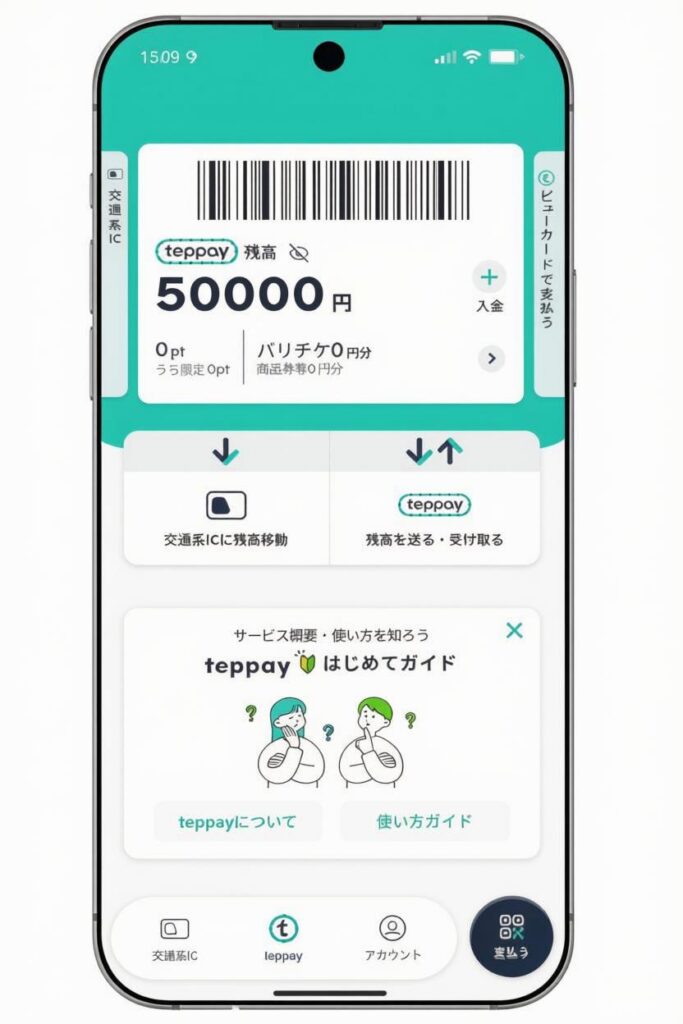
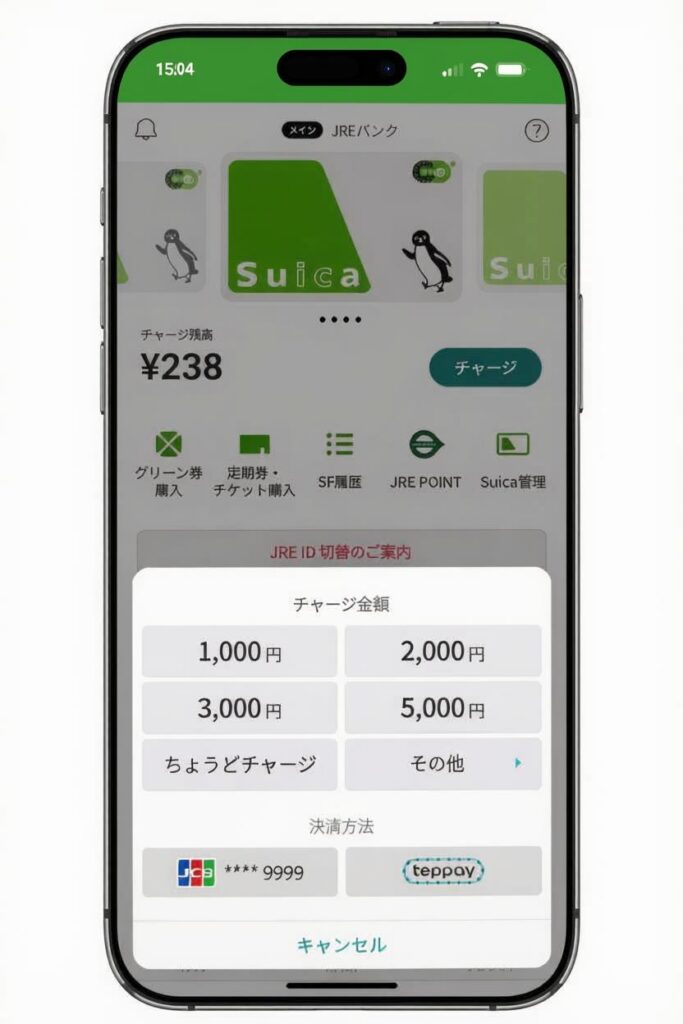
This will be introduced into the Mobile Suica app that everyone already uses. Interestingly, it will also be offered in the Mobile PASMO app next year.
Basically, the way it will work is like this:
1. You can charge your Teppay balance using cash at ATMs (and of course via other methods).
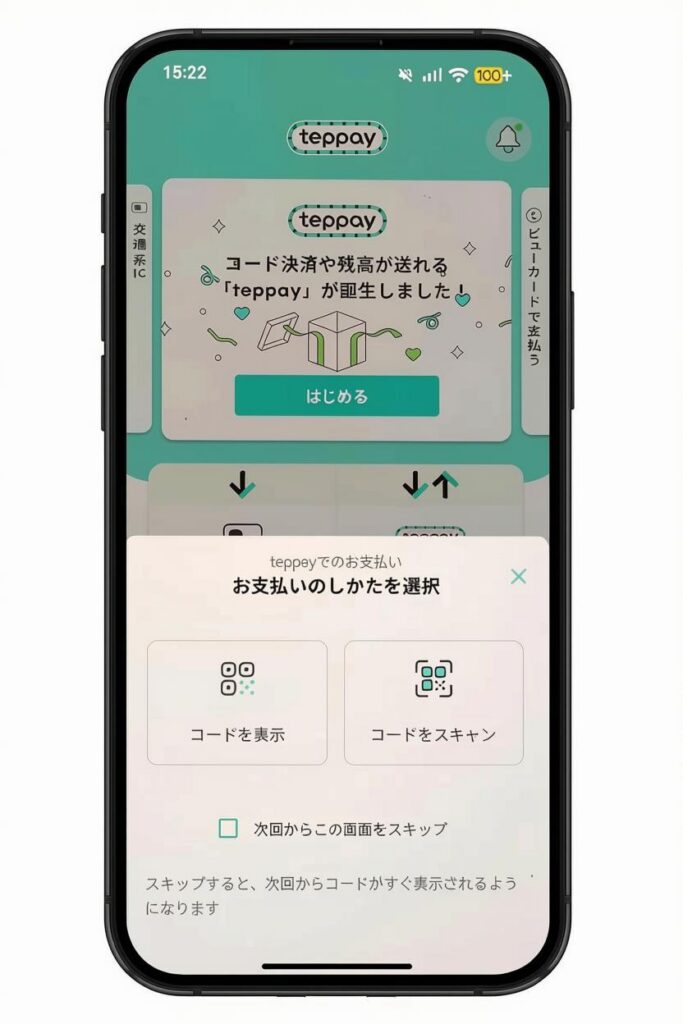
2. You can use your Teppay balance to pay at various stores (via displaying or scanning a QR code).
3. You can also send your Teppay balance to other people with Mobile Suica.
3. You can use the Teppay balance to charge Mobile Suica.
This works well from my point of view:
1. You can use Teppay to pay for large purchases
2. You can use Mobile Suica to pay for smaller, more frequent purchases – and riding the train, of course.
Some notes:
1. Teppay can not be used directly for riding the train without first charging your Suica balance.
2. While you can charge your Suica balance from your Teppay balance, the reverse is not possible.
3. You cannot send your Suica balance to other people.
Given that there are numerous competitors to PayPay at this point, but PayPay is still king, it will be interesting to see how this shakes out. JR has a huge customer base.