Blog

  • Japan Rail’s new QR Code Payment System (Teppay) launches

    Japan Rail’s new QR Code Payment System (Teppay) launches

    Current Market “Pay” (Bar Code/QR Code Payment)

    – PayPay has 45%

    – Followed by Rakuten, dPay and au Pay

    This is a crowded market place, and players are already leaving:

    f.e. Yucho pay (from Japan Post) and Hama Pay (from Yokohama Bank) have already announced their exit from the market.

    Teppay is entering this kind of market, but they have their own unique advantages and disadvantages:

    Advantages:

    – Mobile Suica has 45 Million users

    – No need for an additional app

    – Can charge Mobile Suica from the balance, spend it from a JCB card number for online purchases, or use bar code/QR code payment

    – JRE Point Ecosystem

    Disadvantages:

    – Late market entry

    Some additional Information:

    – The version of mobile Suica with Teppay integrated was released on 2026.10.20 at 11am JST. If you update after that, your app will gain the Teppay features.

    – Some features (f.e. the JCB virtual prepaid card) require you to verify your identity. In practice, this means using your MyNumber card. You will need to know the Electronic Signature password for your MyNumber card in order to complete this step.

    – You can have multiple different accounts on different phones, but only one can be verified through a single MyNumber card. (This is similar to PayPay).

    – There is no mention in the app or on the web site about a way to withdraw cash from the app or transfer it back to a bank account. It would be safe to assume that once you put money in, there is apparently no way to get it back out in cash.


    A Quick Walk-through:

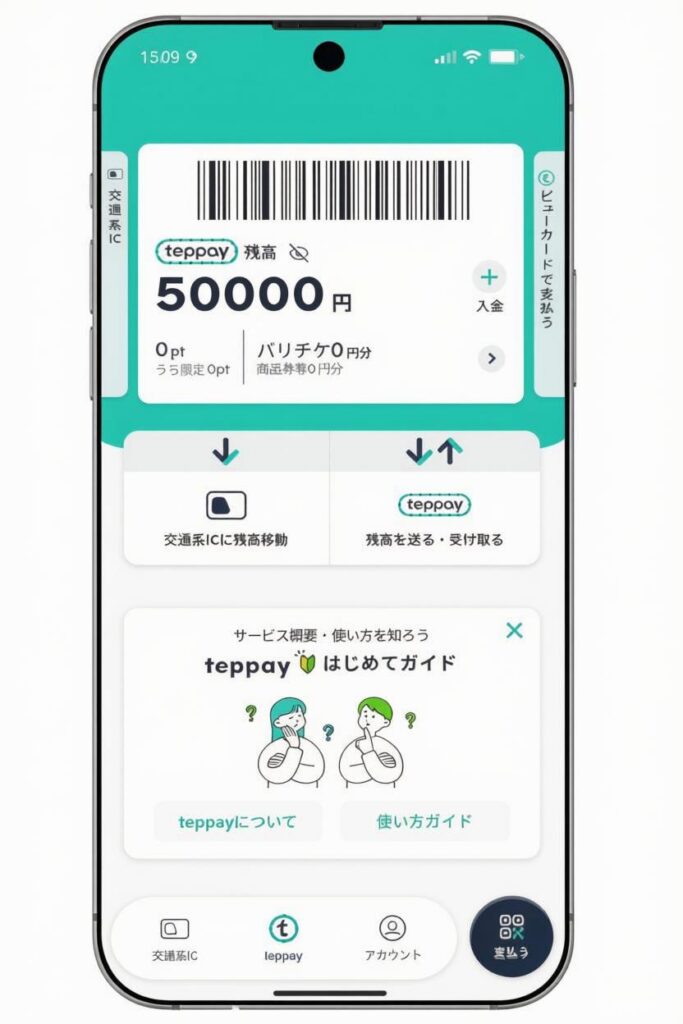
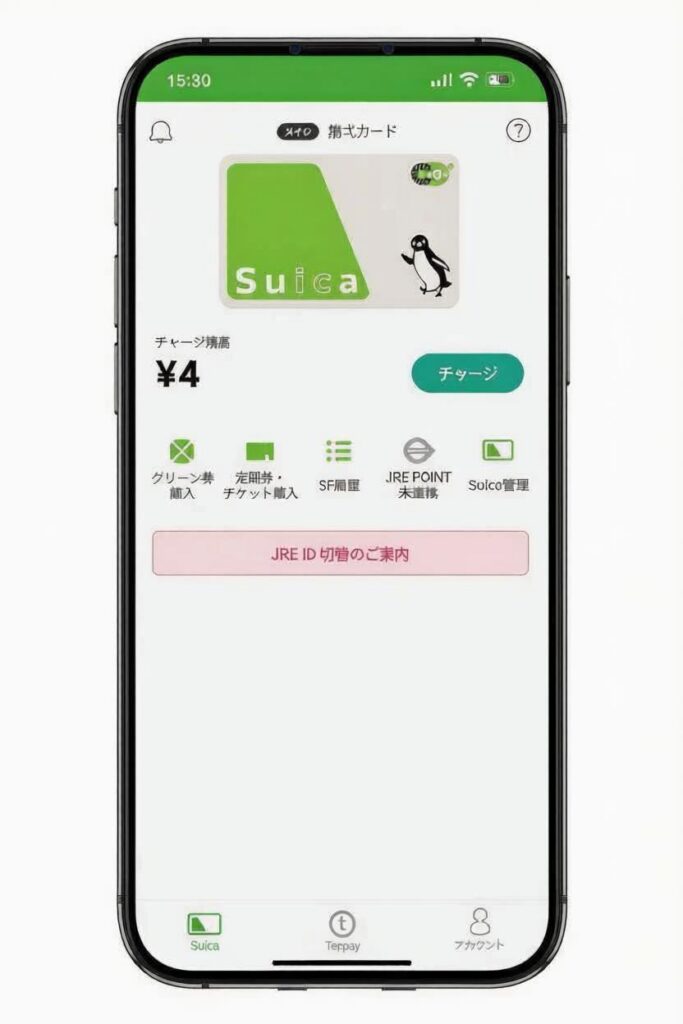
    When you first Open Mobile Suica, everything will look almost the same as usual.

    However, you will notice an icon with a “t” inside a circle in the middle section of the bottom of the screen.

    When you touch this icon, it will change to the Teppay screen.

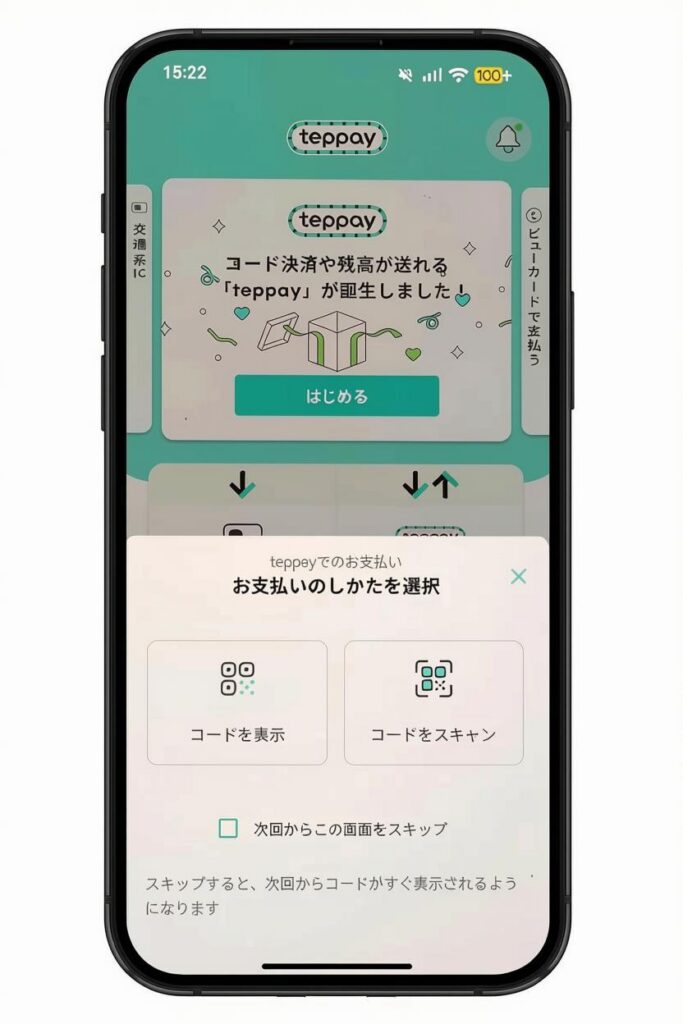
    Even without registering your MyNumber card, you can load a balance onto Teppay from an ATM at 7-11 or other similar stores. Once such a balance is loaded, you can pay using the dark blue payment button in the lower right-hand corner of the screen.

    Touching that button will bring up a screen asking whether you want to display a code (Left), or read a code (Right).

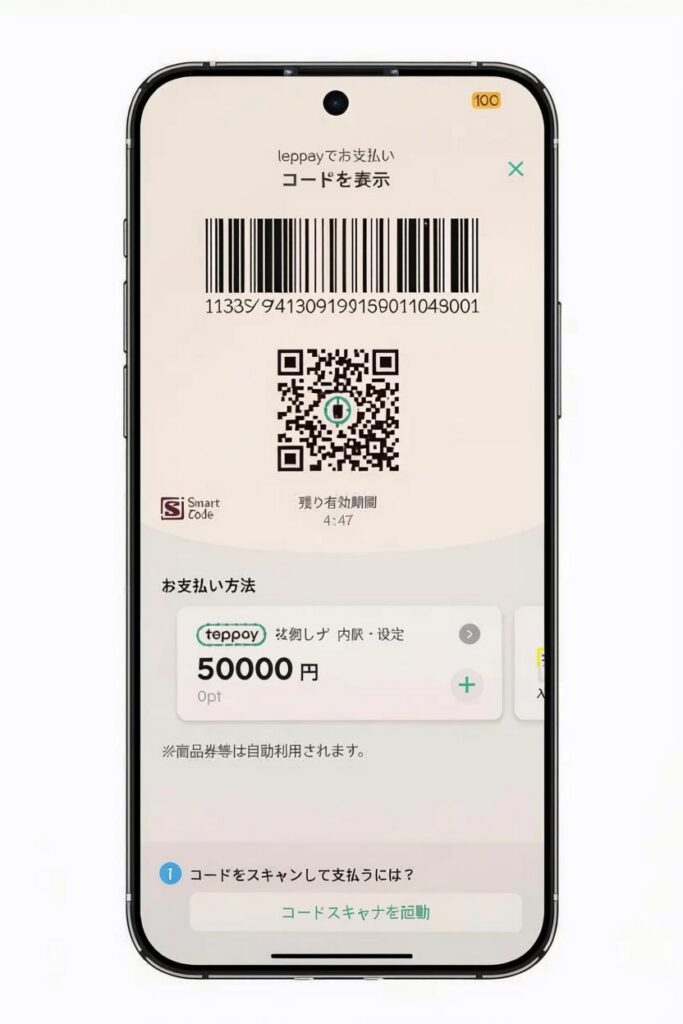
    If you select the option on the right-hand side, the camera will open so that you can scan a QR code. If you select the left-hand side, the following code display screen will open:

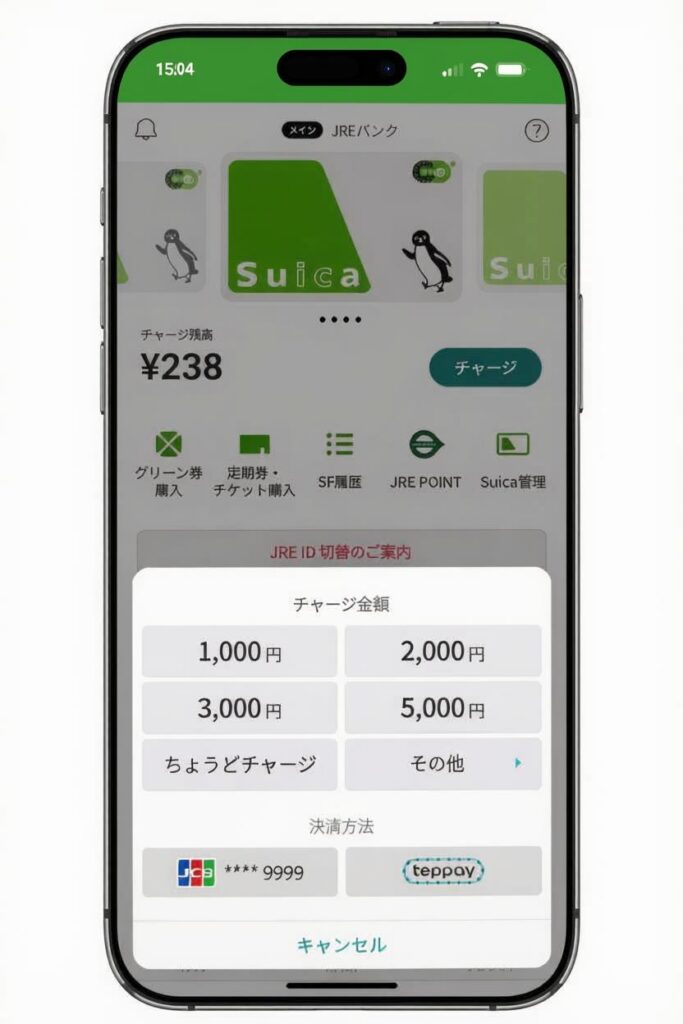
    If you select the (transportation card) icon at the lower left-hand of the main Teppay screen, then it will return you back to the normal Mobile Suica screen. From there, you cal select “Charge”, and you will see that there is now a new option for charging from Teppay in addition to the normal credit card option.

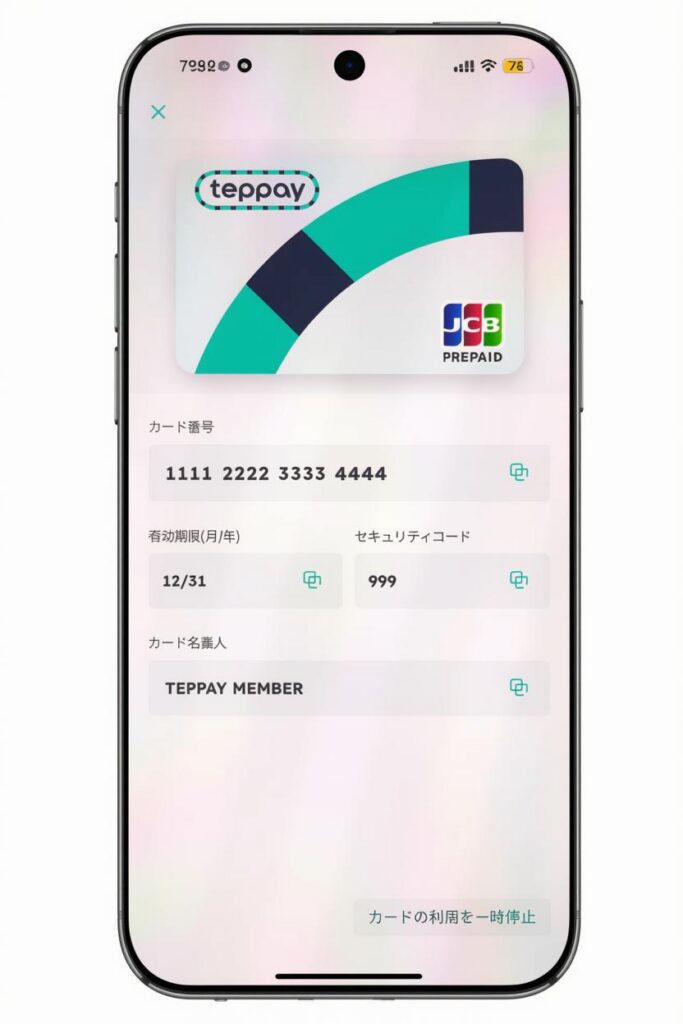
    If you do register your MyNumber card, then you can apply for the virtual JCB prepaid card, which was immediately approved in my case.

  • Modecca Depo – Model Credit Secured Credit Card

    Modecca Depo – Model Credit Secured Credit Card

    I have heard foreigners complain that they are unable to apply for credit cards in Japan because they don’t understand the language, won’t be approved, etc.

    Understanding the language is a point that in the long run you can only resolve by studying Japanese. There are a few financial institutions that support English, but you will always pay more for the privilege. Asking a friend to help you with the Japanese application is generally a better option. Putting that aside, there are some tricks and tips you should know.

    1. If you’ve recently moved to Japan, apply for a card you already have overseas. American Express is a good example. If you apply in person and mention that you have an Amex card overseas already, they will likely put a note on your application and it will probably be approved. I know people for whom this has worked.
    2. Apply for a department store card. For many department stores such as Marui, you can apply for a store only card and the acceptance criteria are lower than for a card with Visa, Mastercard, etc. This is a good option is you have stable employment with a Japanese company and haven’t moved or changed jobs recently. After a year or so they will usually offer to switch you to a global brand card. They will report your usage to the credit reporting agencies in Japan, meaning after you use this card for a few years, you should be able to apply successfully for other cards.
    3. Deposit Type cards. If you are self-employed or otherwise don’t have a steady income and haven’t established credit already, this is a good option to get started building credit in Japan.

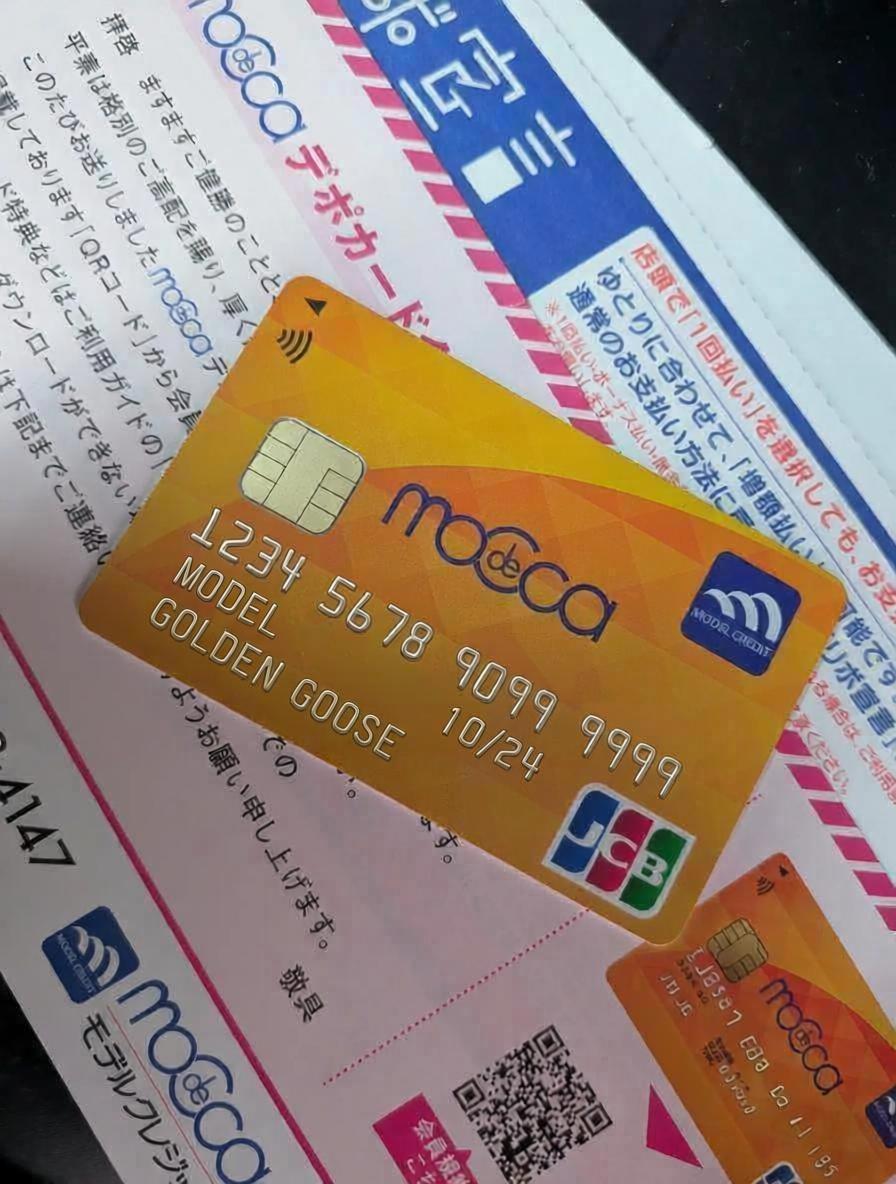
    In the category of deposit cards, there are numerous options, but the cheapest is Model Credit Deposit Card, abbreviated Modecca.

    CardBrandAnnual feePoint rateDeposit range
    Nexus CardMastercard¥1,375/2200 (+¥1,100 issuance)0.50%¥50,000 – ¥2,000,000
    Nexus Card GlobalMastercard¥2200 (+¥1,100 issuance)0.50%¥100,000 – ¥2,000,000
    Luxury Card Titanium Deposit-TypeMastercard¥55,0001.00%¥300k–¥99M
    Nissenren JCB Card DepositJCB¥3,3000.50%¥100,000-¥300,000
    Deposit Type Life CardMastercard¥5,5000.50%¥30k–¥1.9M
    Modecca Depo CardJCB¥1,375 (+¥1,100)0.10%¥30k–¥3M

    Things to note:

    • Nexus Card Global is marketed specifically at foreign residents and pitches applying without a Japanese bank account by paying the deposit. This is the only one we know of with English support. The approval rate is lower than the others, but their application page is here: https://mydeposit.nexuscard.co.jp/
    • Luxury Card is the high end: a metal card with concierge, Priority Pass and dining privileges, where the deposit runs from ¥300,000 up to ¥99,000,000, aimed at people who need large limits but can’t pass a conventional screening.
    • Modecca and Nexus Card have the lowest fees, but Modecca has a lower starting deposit. You can start with as little as ¥30,000 and add more later, which makes it easy to start if you just need to pay for small items. Modecca also claims to have a 95% approval rate.
    • You can also use Prepaid cards and/or Debit cards instead, but deposit cards are good for building credit. Also note that certain merchants will only accept “real” credit cards, and deposit type cards are generally accepted in this case.

    Account Creation Process

    1. Visit: https://www.modecca.co.jp/ and apply on-line. You must register your postal address, email address, and Japanese mobile phone number as part of the application process. They will send a one time password to your email address to confirm that it is valid. You also need to decide on a password for logging into your account. They will send another email with your application number confirming your application once you finish the last page, so make sure to note this down for later.
    2. Once your application has been provisionally approved, they will send you an SMS with a link containing payment information. When you open the link, there will be a payment number that you can use to pay at a convenience store or you can pay online through logging into your online banking account if your bank is supported. (This works similarly to Pay-easy).
    3. After you have paid they will formally approve your application and send you an email with your user name and the URL to log into the web service. They will also ask you to log in and set up 3D Secure. This mainly consists of setting up the phone number you want to be used to confirm purchases. (It doesn’t have to be the same as the contact number you filled in during the application phase).
    4. They will mail the card to you using delivery confirmation. This means the post office will check your ID.

    Once the card arrives, you can use it immediately, but like other deposit cards, you will only be able to use it up to your deposit amount. They will deduct the amount you used each month on the 27th. Sadly, it is not possible to change this date. Please see their page for further details on the billing cycle.

    Advantages:

    • Easy to pass the credit requirements (Most applicants accepted)
    • Low yearly membership fee
    • Low starting deposit (You can get started with Just $300)
    • Helps build credit
    • Prevents over-spending

    Disadvantages:

    • Your deposit money is essentially dead capital. It doesn’t earn interest, and you can’t spend it.
    • The direct debit date is the 27th, and can’t be changed.
    • Despite the fact that they have your money in the form of a deposit, anything other than a one time payment still incurs interest – so make sure to pay off the balance in full each month!
    • Only JCB brand available
  • Banking Paranoia

    Banking Paranoia

    In a installment, we discussed the basic partitioning of your digital life into banking vs. non-banking. This was mainly composed of creating separate email accounts and using separate phones for your banking and non-banking tasks.

    We also discussed password management, maintaining separate email aliases and usernames for each financial service, and several other topics. If you follow all of the advice in the previous installment, then you will be far ahead of most people in terms of your likelihood of having your accounts hacked.

    This is mainly because we have removed banking from your normal accounts, meaning that hacking them will gain the attackers nothing useful. Likewise, since we use the banking related accounts only very narrowly for banking, so they are much less likely leak or get hacked. Finally, since the accounts are separate, it will be much easier to detect things like Phishing.

    A note on VPNs and TOR:

    One thing we didn’t cover was the use of VPNs or privacy systems like TOR.

    The reason I don’t consider this to be a big deal is:

    a. One assumption is that you will use your banking phone and/or do most of your online banking from home or using your mobile data connection.

    b. Basically all of the apps you might use will be using SSL encryption. This means that even if you are accessing your bank account from unprotected WiFi in a coffee shop, the contents of the pages you are viewing, and the data you send back are basically all encrypted. In addition to this, the identity of your bank is verified by the browser (i.e. that the URL matches the SSL certificate), and your identity is typically verified by your login and password. In such a scenario, the only thing an observer can get is the URLs of the site you are accessing.

    If you are still nervous, or want to prevent anyone from even knowing what sites you are accessing, then a VPN might be for you. Using a non-reputable VPN would be worse than using no VPN, though, so I would search for a reputable vendor. I personally think Proton VPN is a good option, but there are plenty of others. One thing to note is that some banks will block known VPN services.

    If you want to protect your traffic in places with public WiFi like cafes, but don’t mind your ISP knowing which sites you visit, you can use something like a Synology router with VPN Plus. Basically speaking, this type of setup will never be blocked, since as far as the bank knows, you will be connecting from your house.

    TOR is a more extreme option that I don’t recommend for even the very paranoid in most cases because:

    1. Many banks block TOR (Some also block VPN, but…)
    2. TOR has a high performance penalty
    3. TOR is usually used to hide from your ISP and/or the government which sites you are accessing, and/or to hide from the sites who you are and where you are connecting from.

    Basically speaking, you don’t need to hide the fact that you do online banking from your ISP or the government, and your bank is going to know who you are once you log in anyway. This means that TOR is a solution for a threat model that doesn’t match the scenario of online banking.

    However, the advice until now was limited to what can be done relatively easily for free. This does leave some weaknesses that could be addressed if we are willing to spend a bit more effort and/or money.

    The first issue is that of MFA/OTP.

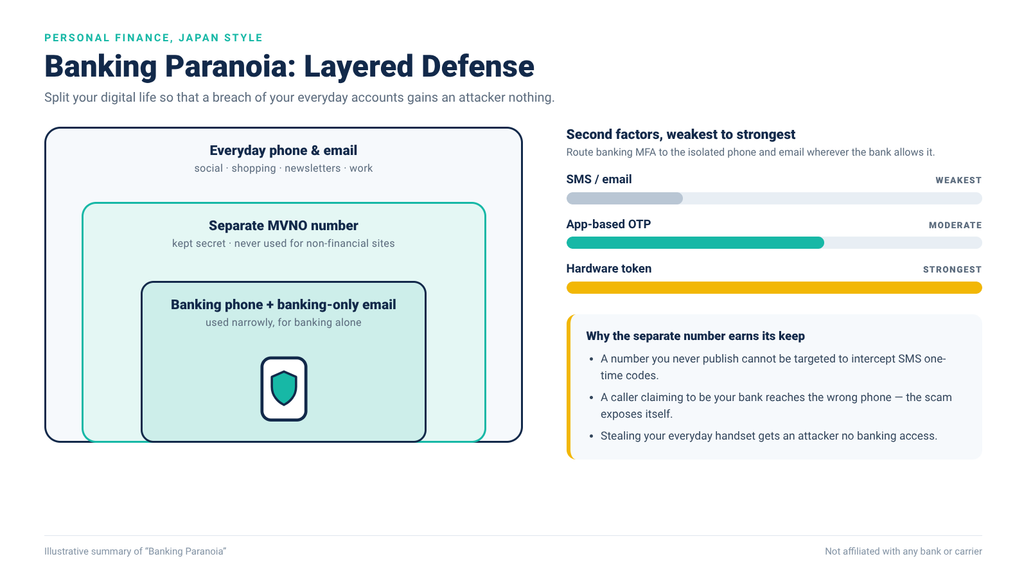
    1. Using SMS for MFA is not actually terribly secure, and so should be avoided when possible. If it has to be used, though, we want to at least make it a separate number from your normal phone number. This lessens the chance that an attacker would know which number to monitor and/or hack, and also means that losing your normal phone would have no impact on your banking life. We have been trying to separate your financial and non-financial life, and this will make the separate complete (at least on the phone level).
    2. Using a one time password app on your phone is not the most secure option (Since at least theoretically, your phone could be hacked). Many banks offer hardware OTP tokens, which are a batter idea for the best security. Aside from that, if you ever need to change your banking phone then re-registering all of the OTP tokens will be a time consuming task. With services like Gmail and Proton Mail, there is no standard OTP token, but there are 3rd party security tokens you can purchase.

    Getting a separate phone number for banking:

    Given that you won’t use your banking phone often, or for watching movies, etc., it doesn’t need to have much of a data allowance. You also won’t generally make calls from it, so it doesn’t need to have a lot of included minutes. It should have SMS and Voice service available, though.

    • If you are in Japan, I would recommend a “Kakuyasu” service like Mineo, Sony’s Nuro Mobile, Povo, etc. With these services, you can get a working phone number for less than 1000 JPY per month – even for free, in some cases.
    • If you live somewhere outside Japan, then of course check your local MVNO and prepaid options to see what would work best for you. The main point is that the service needs have voice call and SMS support, and should be cheap. It doesn’t need to be 5g (or even 4g/LTE), have unlimited minutes, or a huge amount of data – it just needs to work. (In fact, assuming you have WiFi, it doesn’t need to have any data).

    Ordinarily, the process for signing up for these MVNO services is to submit an application online, and wait for your SIM card to arrive. (eSIM might be supported in some cases). Once it arrives, you can and should change the phone number on file with each of your banks and credit cards, especially the number used for MFA. (Having aid that, if you can change the MFA to use something other than SMS, it would be better).

    For maximum security, you should treat this number as a secret and not use it for any non-financial sites.

    Once this is done:

    1. If someone calls your normal phone claiming to be from the bank, you will instantly know that it’s a scam.
    2. If someone steals your normal phone, they can’t use it to receive SMS based OTPs or call the bank.
    3. If someone knows your normal phone number, they can’t use it to hack SMS based OTPs since you aren’t receiving them there.
    4. You can be intimidated or tricked into giving up your OTP while you are away from home since you won’t have your banking phone with you.
    5. No marketing calls from the bank will come to your normal phone. (You can leave your banking phone in silent, or just turned off when not in use).

    Let us revisit the various types of OTP from least to most secure:

    1. SMS / eMail (Can be hacked and intercepted)
    2. App based (Might be hacked)
    3. Hardware based (Basically impossible to be hacked)

    While some sites might only support using SMS or email, by separating these to a banking only phone and email, we have already made things as secure as they can be.

    If your bank, email, etc., uses app based OTP tokens, these can be switched to dedicated hardware tokens from the bank in many cases, a generic hardware token in some cases, and in the worst case, it may be required to continue use a software token. Note that by having the software token on a separate phone with only banking apps, we have already reduced the risk of compromise as much as possible.

    A word about hardware tokens:

    Given that hardware tokens cost money, many banks will not issue one by default, or will try to get you to switch to a software token.

    You can contact your bank to ask if they have a hardware token available. For example, Mitsubishi Bank, PayPay Bank, Prestia, Yucho, and Sony Bank do, but Rakuten Bank does not.

    For things like gmail, proton mail, and other sites that allow the use of a generic authentication application, you can purchase and use a generic hardware token such as a YubiKey, Nitrokey.

    These devices have many features, but the simplest methods are:

    1. You plug in the security token and press a button. The browser will recognize they key and let you log in only if you inserted the correct key and touched the contact. For example, Gmail and many other web sites support this. This is native USB 2FA authentication support.

    2. OTP generator mode. This is a mode where the token will generate time based OTP codes the same as Google Authenticator, Authy, etc. This is perhaps slightly less convenient than

    You can use the same key for many sites, however I would strongly recommend having one key for banking and one key for everything else (If you feel the need to use the key for non-banking sites at all). The main reason for this is in case you lose a key. (You might also want to have 2 keys for banking and 2 keys for non-banking, so that you always have a backup just in case). Ideally, your banking token would be stored in a safe place in your home and never taken outside, so the risk of it being lost should be minimal.

    Basically speaking, a Yubikey or Nitrokey can’t be hacked, so any account protected with it will be more secure. Depending on the key, you can use the same key on the computer and phone, which can be convenient. If you need to change your banking phone at some point, using a 2FA key or similar where possible will reduce the number of accounts you need to re-register.

    Using a hardware 2FA key to protect your email accounts will also mean that email based OTP verification (like Rakuten bank uses) will be that much more secure.

    Finally, the type of email aliases we introduced in the last installment (Plus aliases) are workable, but not ideal – mainly because they can’t be disabled, and they reveal your “real” address. A better option would be to use real aliases that the email server recognizes and forwards to your main banking address. This can be done with services such as SimpleLogin.me, although using more than a certain number of addresses will typically involve a small fee.

    Let’s take a look at the whole budget:

    One Time:

    a. Banking USB 2FA hardware security token and backup : 5,000 x 2 = 10,000 JPY

    b. Bank specific OTP Tokens : Varies (often free)

    Recurring:

    a. Proton VPN : Free plan

    b. Proton Mail: Free Plan

    c. Gmail: Free Plan

    d. Kakuyasu MVNO SIM card: 1,000 JPY / Month

    e. SimpleLogin.me or Proton Pass for email Aliases: 500 JPY / Month (alternatively, AliasVault or Apple’s Hide-My-Email for free)

    So, we are looking at a one-time expense of around 10,000 (assuming you get your banking phone for free by using your old phone, etc), and also a monthly fee of around 1,500 JPY.

    That means you can lower your chance of being hacked to effectively zero for less than 20,000 per year. Given that getting hacked or tricked even once will likely cause damages exceeding this amount and cause much time and effort to recover from, this would seem to be a very good trade-off for many people.

    The final step I want to discuss is the physical separation of accounts.

    Many people have a number of credit cards, and also may have a main bank account where their payroll is deposited, they take cash out of, use their debit card, etc. This can be quite dangerous for numerous reasons:

    1. Your credit card number could be stolen.

    2. Your card could be lost or stolen.

    3. You could be threatened into giving up your PIN.

    4. You might fall prey to impulse shopping.

    5. You might accidentally spend too much.

    The main point is that you don’t need to carry around high limit credit cards or bank cards with you on a daily basis, and doing so is a high risk activity. Would you rather lose a credit card with a 50,000 JPY limit, or one with a 5,000,000 JPY limit? If you are just going shopping, there is no need to carry multiple cards, or large limit cards. In fact, ideally you should carry prepaid cards instead of credit cards, so that your losses are limited to the balance, but if you do carry credit cards, it’s best to limit to 1 or 2 with small limits. (Some people will point out that many credit card companies will cover losses due to fraud, but they don’t necessarily realize that recovering from identity theft and providing all of the evidence that the credit card company or bank requires can be a long and difficult process. Furthermore, if a PIN was used, they may not reimburse you at all).

    I know people who have been overcharged by thousands of dollars and not had recourse. This wouldn’t have happened if they were’t carrying cards that had such high limits (their card would simply have been declined instead).

    Worse, cash cards and debit cards are even more dangerous because they typically have fewer fraud protections, and transactions happen in real time. As an example, if you lost your debit card someone could potentially use it to purchase thousands of dollars worth of goods, which would mean that now you have no money left for your rent or mortgage, etc., and you may not be able to get the money back. In an ideal world this wouldn’t happen because charges wouldn’t be approved without your PIN, and an attacker wouldn’t know your PIN – but in real life, things happen.

    This means that carrying a debit card which has access to a bank account with more money than your spending money carries a high risk. A recommendation would be to set up a separate bank account for spending money (pocket money), and transfer money into that account after each paycheck. Carry your spending only card, and leave your payroll bank card at home. Likewise, use this pocket money card when shopping online. This way, you can’t overspend, and your losses are limited should you lose your card, your number is leaked, etc.

  • Playing the Game

    Playing the Game

    I want you to close your eyes and think of a game.

    • If you’re into sports, think of a team sport like volleyball, soccer or baseball.
    • If you like card games, you can imagine poker or any other game where skill plays a large part.
    • If you like board games, perhaps monopoly will do.

    A few other caveats:

    • Imagine you are up against a highly successful processional team who has been consistently winning at this game for years.
    • Now, imagine they haven’t explained the rules of the game to you – nobody has.
    • Finally, you’re wearing a blindfold.

    Good luck!

    Yeah, the chances of you winning are pretty low. It’s as if you showed up to a soccer game with a baseball bat and didn’t know that the object of the game was to get the ball into the opposing team’s goal.

    Yet, that’s often how it is with personal finance and wealth building.

    The deck is heavily stacked against you:

    1. First, it’s hard to know what to do in order to get a high paying job.
    2. Is college the answer? It’s hard to get through college without paying far too much. Student loan companies want you to borrow more so they can profit, and schools want you to borrow so you can pay them more.
    3. Then, once you get a job, it’s hard to know how to avoid paying more taxes than necessary.
    4. There is an army of marketers with huge budgets out there who spend their time all day, every day trying to come up with ways to get you to spend money on the products and services they pedal. Their job is to convince you that you need that new shirt or smart watch or car or… whatever, and you need it now. You have to have it, and it can’t wait!
    5. Then there is another army of people who work in consumer finance companies. Their only goal in life is to get you to borrow money from them so they can profit off of the interest. That thing you have to have now? You can pay for it later. (You’ll end up paying more, of course… but don’t worry about that).
    6. When you decide it’s time to find your own housing, there is no shortage of unscrupulous landlords, property management company, and real estate agents who will be more than glad to deprive your of your money. Getting you to buy high and sell low is their real priority – but they make a hefty commission either way!
    7. Insurance companies will pray on your fear of uncertainty and death to overcharge you for insurance that you don’t need.

    Worse yet, once you decide to save money or invest, people are out to fleece you there too!

    1. Brokerages are happy to sell you the dream of day trading, because they make profits whether you buy or sell, and are all too happy to encourage you to do so as often as you would like – even if that costs you more in taxes. They are also only to happy to lend you money on “margin” – that’s right! You too can borrow money to bet on stocks! You may as well use your credit card to load up on Lottery Tickets, Pokemon Cards, and Beanie Babies to make your fortune.
    2. Assuming you’re smart enough to avoid day trading, FX, Crypto, binary options, and all of the other hype swirling around the cesspool of get-rich -quick schemes, and invest in a NISA or 401k – that’s when the high cost rip-off mutual fund advertisements start. Fund marketers have spent decades honing their techniques to make it look like investing in mutual funds might somehow provide you with enough returns to outweigh the expenses – even though they know it won’t. If you complain after losing money with them, they can always say “We told you past performance isn’t a predictor of future returns…”

    I could go on, but I think you get the point by now. Everyone is always out for your money all the time. You knew that already – but bear in mind that they have people with PhD degrees in psychology designing experiments to see if they can take just a little bit more of your money, while you are being tracked online by the likes of Google and Amazon to make sure they extract every last bit of money they can, like hungry wolves sucking the last bit of marrow out of your bones.

    If they think they can get you to spend more money because if your heritage, country, depression, pregnancy, time of day, desire to fit in, political affiliation, day of the month, lack of self confidence, divorce, fear of missing out, marriage, etc., it doesn’t matter – whatever it is, they will try to track it and exploit it.

    So you have companies monitoring your education, employment, and purchase history, current location, etc., while other companies perform A/B testing and apply the latest psychological theory to develop the most effective marketing campaigns. Then they combined these two things together to target you individually. This massive and sophisticated weapon is aimed squarely at you, and your defense is?

    If you were extremely lucky, you might have had some sort of personal finance course in high school or college, where you learned boring words like “budgeting” and “401k” – just at the time you were occupied with other studies tons of other things more interesting.

    You come out of the educational system knowing next to nothing about reach financial security, meanwhile your parents can’t teach you much if they are living paycheck to paycheck themselves.

    You learn platitudes like “Love can’t buy happiness” and accept “The Rich get Richer and the Poor get Poorer” as a truism, and just give up.

    This might all sound like a crackpot conspiracy theory – except if you read each point, you can verify that they are true. It’s pretty much common sense that everyone wants to take your money, it’s just that not everyone realizes the mechanisms in use.

    My pain point here is that the reason most people don’t “win” at the game of personal finance, is that nobody has even taught them the rules.

    For example, if the average person believes wealthy people buy expensive watches and cars to show off their wealth, then they may buy expensive watches and cars too – which, ironically, will prevent them from ever being wealthy.

    In general, if someone (especially some company) wants you to do something, it’s because it’s good for them – which often means it’s bad for you. Keep that in mind next time you are offered a “special promotion” or “exclusive deal”.

  • Interest Rate Hikes – Winners and Losers

    Interest Rate Hikes – Winners and Losers

    In the last entry, we mentioned that interest rates rise and fall as a matter of course, and that the recent extended period of very low interest rates was a historical anomaly.

    We also mentioned that higher interest rates are neither good, not bad, but that different parties benefit from each – so who are the winners and losers from the recent rate hikes?

    Winners:

    1. Banks and other financial institutions. Banks make money on interest. Even to the extent that they need to pay interest, higher interest usually means a wider spread.
    2. Insurance Companies. Insurance companies invest the money they receive as premiums, so a higher interest rate means they earn more on the money they have invested.
    3. Cash Rich Companies. Any company in any industry that has a large amount of cash will do better when interest rates rise. Not only can they make more money by investing their money in things like government bonds, but they can take advantage of opportunities that companies with debt cannot.

    Losers:

    1. Heavy Industry. Industry that requires a large investment in equipment typically requires than companies take on significant debt to fund that equipment. When debt gets more expensive, the cost of servicing that debt increases, and their profits naturally decrease.
    2. Research & Development Heavy Industries. Like heavy industry, companies that depend heavily on research & development typically rely on debt as part of the funding mix that supports that research.
    3. Real Estate. Financing becomes more expensive for both builders and purchasers. This bleeds over into construction and other areas related to real estate.
    4. Utilities. Utility companies like TEPCO and Tokyo Gas typically have huge amounts of debt from financing massive distribution networks.
    5. Highly Leveraged Companies. While money was free, many companies have taken on debt to fund expansion, new product development, etc. Now with interest rates rising, debt payments will rise, and free cash flow will suffer.
    6. Discretionary Consumer Products & Services. As consumers suddenly find themselves needing to spend more money on mortgage and other debt, they may decide to eat out less, and buy fewer optional items. This includes everything from upgrading consumer appliances and buying new clothes, to going on vacation. When your monthly bills increase, you may find yourself reconsidering whether you really need the latest smart phone or decide that you can put your family vaction on hold for a year.
  • Interest Rates are Variable – Duh!

    Interest Rates are Variable – Duh!

    It makes me laugh when people act surprised that interest rates have risen in Japan recently, but it wasn’t that long ago that a real estate agent trying sell me on using a loan to buy property said “Rates rising in Japan? That is unfathomable! It could never happen!”

    That guy was probably in his mid-twenties, and had only been in the workforce for around 5 years. To him, interest rates had been near zero for his entire working life, and he couldn’t imagine things being any different

    The reality is though, that interest rates of course change over time. They are the “Variable” in terms like “Variable interest rate loan”. They have been high before, and so of course they would be high again.

    In fact, the central banks and the government have only a few levers they can pull to move the economy in the direction they want. They can print money, buy money, raise or lower taxes, hand out stimulus checks, increase or decrease public spending, or … raise or lower interest rates.

    The fact that interest rates had been so low for so long wasn’t a sign that Japan was somehow special, so much as it was an unusual state that has now been corrected.

    Central banks usually lower interest rates in order to encourage spending and speed up the economy. When things speed up too much and it looks like the economy is heading into a bubble (which would eventually lead to a crash), the government will raise interest rates to slow things down. When growth is slower than they would like, they will lower interest rates so that it’s easy to borrow money. This encourages people and businesses to spend and causes the economy to heat up again.

    Only, in Japan, even a zero percent interest rate didn’t heat things up as much as the government would have liked – so it stayed around zero for a long time. To put it another way, GDP growth, wage growth, and inflation stayed around zero, and so the central bank kept the interest rates around zero too.

    So what changed?

    1. Inflation went from very low to quite noticeable in a short period of time. Some of this was due to rising energy prices as a result of wars overseas. Some of it was due to the weakening of the yen. There are multiple causes, but the important thing is that it exceeded the target that the Bank of Japan had in mind.

    2. The exchange rate started to shift rapidly. This was caused in large part by increasing interest rates in the United States and other countries. Many countries had lowered interest rates during COVID, and started to increase rates again recently. Once the spread between interest rates you could earn on Yen and Dollar became large enough, investors were willing to take the currency exchange risk to invest in USD and earn a higher interest rate. When this happens on a large enough scale, the net effect is to lower the value of the Yen relative to the Dollar.

    In order to slow down the selling of Yen to buy dollars, the Central Bank had to make interest rates more attractive in Japan.

    The moves made by the bank of Japan so far have actually been quite timid. One reason for this is that there are benefits to having a cheap currency, too. For example, there are still large exporters in Japan, and they typically benefit from the cheap yen. Another reason is that not only will increased interest rates slow down an already slow economy, but they will also cause hardship to those with large loans (such as mortgages). To be fair, though, anyone who buys a house with a variable rate loan should be prepared for such a thing! Finally, making small, incremental changes allows the Bank of Japan to gauge the effects before proceeding.

    The point here isn’t to explain every detail of how these complex interactions work, or get deep into economic theory. I just want you to understand a few simple points:

    1. Interest rates go up and down. It’s normal. Nobody should be surprised.
    2. Currency exchange rates also go up and down. Nobody should be surprised.
    3. Inflation goes up and down. Nobody should be surprised.

    Hyperbole like “It’s the Highest rate in X years!!!” is silly, and misses the point. It will always be the highest, or lowest in X years – you just have to change X to match the current situation. What’s more, any high or low marks will be broken eventually.

    Then there are two more important points:

    4. High (low) interest rates aren’t inherently good or bad. They are good (bad) for different parties.

      5. High (low) exchange rates aren’t inherently good or bad. They are good (bad) for different parties.

      From a personal perspective:

      – If you have lots of credit card debt and you want to go on a vacation overseas, then you want a strong yen and low interest.

      – If you have lots of cash in the bank and you sell things to tourists, you want a weak yen and high interest.

    1. A new QR Code Contender: Teppay

      A new QR Code Contender: Teppay

      The original Suica card came out in 2001, back when smart phones as we know them today didn’t exist. Later, the ability to have a Suica card automatically recharge from a linked View Card was introduced, and with that advancement, the need to charge at a ticket machine was removed from the equation. Most people used cash to charge at ticket machines, so the need to use cash was also removed.

      A few years later, Mobile Suica was introduced, which allowed members to use Suica on their phones, without the need to carry a card. By this time, many stores around the neighborhood, and all stores in the train stations accepted Suica as a payment method. Mobile Suica could be charged on your phone (via credit card), and you could tap your phone to pay as well.

      Suica competed with Edy, QuickPay and iD – the latter two of which were at the time always linked to credit cards, and so post-pay methods. Suica, Edy, Waon, and Nanaco on the other hand, are pre-paid. In fact, they don’t just act like prepaid cards, the balance is actually stored on the card.

      This means that Suica (including mobile Suica) has some inherent advantages over other schemes.

      1. You don’t need internet (f.e. mobile coverage) to pay. You have full payment functionality without needing internet.

      2. You need internet to charge Mobile Suica on your phone via a credit card – both both your phone and cards (as well as smart watches, etc). can be charged at ATMs, convenience store counters, and some ticket machines via cash.

      3. You don’t need to create an account, show your ID, or register any credit card or bank account in order to create a normal, unregistered Suica card, or basic Mobile Suica account. This means anyway can always create and use Suica. This includes tourists and other foreigners, people not eligible for credit cards, etc. Suica can be as anonymous as cash.

      4. Suica still works perfectly fine in card form, which makes it easy to have multiple cards. Tellingly, you can add up to 20 cards per person to the JRE Point system.

      Each Suica card (Physical or mobile) can hold up to 20,000 yen, and the balance is guaranteed for 10 years. Suica is accepted at most places, is compact, is run by a very large company not likely to go bankrupt and disappear. It can take advantage of the internet (i.e. mobile charging and online purchases via Suica Pocket), while working just fine with no internet access.

      It can be used 100% anonymously, but also supports registering your name and phone number for peace of mind if you prefer. This means you can combine the privacy and anonymity benefits of cash with the convenience of cashless payments. Or, you can set up automatic charging from a credit card, register your cards to protect against theft, and with JRE Point service, you can even be paid for the privilege.

      What’s more, while most modern smart phones have a limit of virtual 4 cards per phone, there is no limit to the number of physical cards you can purchase. You can safely store your money in Suica, and buy as many cards as you like.

      Suica is not the perfect payment method, though. It was created to handle transportation payments. While it works great for shopping at the grocery store, convenience stores, and vending machines, the 20,000 limit per card can prevent you from making large purchases.

      This limit is necessary, though, because again, the balance is stored on the card. Suica uses a Sony technology called Felica, and it’s not impossible that a card could be hacked. Granted, it would require meticulous dissection by someone with technical skill and expensive equipment. I mean if you are an expert in electronic hardware and encryption and have access to an electron microscope, anything’s possible, I suppose.

      In order to make sure hacking the cards is not worth anyone’s time and effort, the value is capped at 20,000 yen per card, which is still plenty enough for everyday shopping, and taking public transportation.

      Another problem with Suica is that not all foreign phones have the Felica hardware, which means that foreign tourists often couldn’t use Suica. (Previously, another hurdle was that only a few approved Japanese credit cards could be used to charge Mobile Suica, though apparently that has been improved with integration with Apple Pay and Google Pay).

      Also, there have been times during the semiconductor crunch when new Suica cards couldn’t be purchased. This was a temporary situation, but still not ideal.

      Recently, though, there have been two new contenders:

      1. Visa Touch and its ilk

      Honestly, I am not impressed.

      Visa Touch can’t do anything iD or QuickPay can do. The sole advantage is that Touch can be used overseas in many countries. Well, so can the CHIP&PIN payments. I can handle inserting a credit card while I am overseas.

      Too little, too late. Why should I want to use Visa Touch over iD or QuickPay? They are supported by fewer merchants in Japan, and typically cost more (which results in lower point ratios, cashback etc.)

      Still, some people have gone this route. Even more amazingly, some train companies have started accepting “touch” cards for train fare. Normally the fees Visa and the others charge would be high enough to make this uneconomical, so I can only imagine they are offering low rates for now. Still, if one day iD, Suica, and the others die out – well then I am sure they wouldn’t hesitate to raise their rates!

      Compared with Suica itself, Visa Touch, iD, and QuickPay also offer higher payment ceilings, since they all are postpaid and contact the bank (hence taking longer to process than Suica or Nanaco).

      2. PayPay and other QR Code Payment systems (f.e. Yucho Pay, au Pay, etc).

      These systems have come into being recently, and only really work because of the ubiquity of smart phones with always on internet.

      These are also prepaid like Suica, but instead of using fancy Felica or NFC hardware, they just use QR codes on the screen or store sign. What this means is that a normal phone camera and screen are enough to work properly.

      The QR Code can change every few seconds for security – so showing the right code at the right time is proof that you are the owner of the account. These work primarily online, which means that the smart phones don’t need to hold much in the way of secret data. The servers can check the account holder’s balance and authorize transactions much like credit card companies do for online transactions.

      Since these only work on smart phones, you need a smart phone or similar device. There is no PayPay QR code card. Such a device would have to have a camera, screen, and internet – which is difficult and expensive in a credit card form factor.

      That means that in practice, anonymous payments via PayPay and similar schemes are difficult. They will let you sign up without providing ID, and you can charge using cash – but the limits will be low until you verify your ID with them.

      This may be a good thing too, since while possession of a Suica card is enough to prove ownership, what do you do if you had a large balance on your unregistered paypay account and you acidentally reset your phone or deleted the app?

      Still, the QR code payment schemes do have some advantages.

      One advantage is the lack of need for any specific terminal hardware. A small mom & pop shop can simply print out a QR code and slap it on a sign after registering for a merchant account. The startup fees are close to zero. Compare this with getting a terminal that can process Suica cards.

      PayPay is especially advantageous for merchants compared traditional credit cards. Merchants usually end up having to pay several percent of gross proceeds to credit card processors. (Where did you think your points and cashback were coming from?) While this is lower for Suica, it’s apparently even lower for PayPay and similar.

      They don’t need to issue costly IC cards or manage special terminals. Even charging by cash is handled by ATMs, so no charging terminals to maintain either. Then there is no processor-bank-card split – basically, it’s all one company if you use PayPay. It’s easy to imagine that PayPay and similar services have lower running costs than legacy credit card companies.

      Also, if you want to send money to a friend, you can easily do that with PayPay. That’s something that isn’t possible with Suica, or with credit cards in general.

      QR Code payment systems also naturally work online, as issuing a special temporary URL to authorize your balance isn’t much of a stretch when you need to be online anyway. Mobile Suica can be made to work online as well, but needs to go through the app (since the app needs to deduct the balance from the hardware on your phone!), and it is not widely accepted.

      For me: I distinctly dislike needing to take my phone from my pocket, unlock the screen, open an app, and display a QR code every time I make a purchase at 7-11 or so. I value the ability to charge with cash, keep multiple cards, and work offline. I like the ability to leave my phone at home and go for a run with a Suica card in my pocket in case I need to buy a drink.

      However for peer to peer payments and larger purchases, Suica doesn’t cut it. Likewise, there are some merchants that are otherwise “cash only” who accept PayPay because it’s easy and low cost to do so.

      In those situations, paying by credit card (via Chip & Pin, iD, or “Touch”) or bringing cash are still the main methods available. After all, BitCoin has failed miserably as a currency.

      Japan Rail has recognized this, though, and… on October 20th, 2026, they are releasing the oqn QR Code Payment system, Teppay. One can only assume this stands for “Tetsudo Payment”.

      This will be introduced into the Mobile Suica app that everyone already uses. Interestingly, it will also be offered in the Mobile PASMO app next year.

      Basically, the way it will work is like this:

      1. You can charge your Teppay balance using cash at ATMs (and of course via other methods).

      2. You can use your Teppay balance to pay at various stores (via displaying or scanning a QR code).

      3. You can also send your Teppay balance to other people with Mobile Suica.

      3. You can use the Teppay balance to charge Mobile Suica.

      This works well from my point of view:

      1. You can use Teppay to pay for large purchases

      2. You can use Mobile Suica to pay for smaller, more frequent purchases – and riding the train, of course.

      Some notes:

      1. Teppay can not be used directly for riding the train without first charging your Suica balance.

      2. While you can charge your Suica balance from your Teppay balance, the reverse is not possible.

      3. You cannot send your Suica balance to other people.

      Given that there are numerous competitors to PayPay at this point, but PayPay is still king, it will be interesting to see how this shakes out. JR has a huge customer base.
    2. Free bank to bank transfers with AirWallet

      Free bank to bank transfers with AirWallet

      Japanese banks don’t generally charge fees simply for maintaining an account, and they also don’t typically require a minimum balance or charge fees for things like failed debits, etc. Whet they do charge fees for are things like furikomi transfers and ATM withdrawals.

      Typically, these may be free under certain conditions, but when making lot of transfers you will often end up paying fees.

      Many banks have some sort of “rank” system where you can get more free transactions if you meet certain conditions – but if you use separate bank accounts for separate purposes then it may be difficult to meet these conditions.

      For example, you might have a “Payroll Deposit” account, a savings account, and a “Spending account”, and a mortgage payment account. Your payroll deposit account may have a low average balance, your savings and mortgage accounts may have few transactions per month, and your spending account doesn’t have payroll deposit.

      This means that you probably won’t quality for the highest rank at any of your banks, and therefore will have a limited number of free furikomi transfers.

      What to do?
      There are various methods to move money between accounts at different banks for free. Today we will discuss a solution called “AirWALLET”.
      AirWallet is an app produced by MUFG and Recruit. Like many financial apps, it is not well defined in that it has multiple features which overlap with other products:

      1. The main feature is the “Coin+” QR code payment method. You can charge your account from a normal bank account, and then pay via Coin+. In this way, they are trying to compete with PayPay, Yucho Pay, etc.
      2. You can also generate a virtual debit card number, which you can use for online purchases. You can request a physical chip & PIN debit card be issued as well. It should be noted that this debit card does not support recurring payments, or shops such as hotels and gasoline stands where the value is not exactly computed ahead of time.
      3. You can send money to friends & family, etc.
      4. Withdraw funds back to a bank account.

      How does AirWallet stack up to the competition?

      • QR Code Payment – To be honest, the QR code payment feature is nowhere near as widely accepted as PayPay, so for QR Code payments, you are better off using PayPay in general.
      • Prepaid Card – There are much better prepaid credit cards available which do handle things like recurring payments. For example, Kyash. Likewise, there are prepaid cards which support iD, such as dCard Prepaid.
      • Sending Money – There are Plenty of ways to send money to friends and family, from PayPay to Kazoku no Saifu, and even normal furikomi. If it’s sending to random people we are talking about, then Furikomi and PayPay (for small amounts) are your best bet. Everyone has a bank account, and PayPay has a large market penetration. Something like Kazoku-no-Saifu or OneBank’s “Pair” account are ideal for family members.
      • Withdrawing funds – This is the best feature. AirWallet supports a large number of banks for both charging and withdrawel. For example, PayPay Bank, Docomo SMTB Bank, Rakuten Bank (Including JRE bank), and more. Sony bank is notably absent at the moment, but Yucho (JP Post) and the mega-banks are all present as well as most of the major net banks.
        Why is this an important? Because both charging and withdrawel are currently free in all cases with AirWallet. This means that you can transfer money from one bank account in two steps:
      1. Charge – Choose an account and select charge.
      2. Withdraw – Choose a different account and select withdraw.
        The charge step is basically instant, and depending on circumstances, the withdraw step can be instant as well.
        This means that if you have a number of transfers that need to be made each month and you often go over your free limit, you can reorganize things so that transfers between your own account are done for free via AirWallet, and save your free furikomi transfers for external transfers to your landlord, etc.
        Is charging money only to immediately withdraw it considered abuse? No, in fact AirWallet is advertising this as a feature, not an unintended side effect.

      Before:
      Furikomi:

      1. Transfer Payroll Account -> Spending Account
      2. Transfer Payroll Account -> Mortgage Account
      3. Transfer Payroll Account -> Credit Card debit Account
      4. Transfer Payroll Account -> Savings Account
      5. Transfer Payroll Account -> Other External Transfer

      After:
      Furikomi:
      2. Transfer Payroll Account -> Mortgage Account
      3. Transfer Payroll Account -> Other External Transfer
      AirWallet:
      4. Charge from Payroll Account
      5. Withdraw to Spending Account
      6. Withdraw to Credit Card debit Account
      7. Withdraw to Savings Account

      From this, we have reduced the use of Furikomi from 5 times to only 2. This is enough to (for example) fit within the 3 free transfers given by PayPay bank for having your payroll deposited there.

      There are other free transfer methods:

      MethodProsCons
      Furikomi TransferFast, Standard, can be scheduled*1Not always Free
      Scheduled Debit*2FreeSlow and inflexible
      Furikae TransferFast, FreeOnly within same bank
      AirWalletFast, FreeManual, Doesn’t Support all Banks

      *1 Furikomi transfers can be scheduled to run automatically with some banks, f.e. PayPay Bank, Rakuten Bank, and Docomo SMTB Net Bank.
      *2 “Scheduled Debit” is the name I am using for “定期自動入金サービス” (from PayPay bank) and similar schemes form other banks, including Docomo SMTB Net Bank. Typically a monthly schedule must be set up according to the bank’s option (f.e. 5th or 27th of the month), and the money is unavailable for at least four business days. au Jubun Bank and Aeon bank also have a similar service.

      Now, you might ask “PayPay also lets you charge and withdraw money, can’t you do the same thing?” Well, yes… and no.

      Account TypeCharge from Bank AccountWithdraw to Bank Account
      PayPayFree145 JPY*1
      Mercari PayFree200 JPY
      AirWalletFreeFree

      *1 PayPay withdrawals to PayPay bank are free. Withdrawals to SMBC bank are free up to 5 times per month. Otherwise, withdrawals cost 145 JPY.

    3. Deposit Type Credit Cards in Japan

      Existing payment options in Japan

      If you want to pay for purchases in person, you have many options like:

      • Suica, Pasmo and other transportation cards (and mobile variants)
      • Waon, Edy, and other non-transportation oriented prepaid IC cards
      • PayPay, J-Coin, Yucho Pay, au Pay, MerPay, and other QR code based solutions
      • You also have prepaid credit cards like SMBC Visa Prepaid, Kazoku-no-saifu, dCard prepaid, Kyash, OneBank, au Wallet, and more.
      • There are virtual only and virtual first prepaid solutions, such as Air Wallet, Bandle, etc.
      • You have debit card solutions from various banks, which fall into J-Debit, and credit card style debit cards (using JCB, Visa, Mastercard, etc).
      • Japanese credit cards, debit cards, and prepaid cards often support Japanese contactless payments in the form of iD or QuickPay, whereas “touch” payments from Visa/ Mastercard/ JCB are less popular in Japan but increasingly supported recently.
      • There are shop specific credit cards and prepaid cards (i.e. Marui shop credit card, and Summit deposit/point card).
      • You can buy things pay using Payeasy or similar solutions where you pay at the convenience store.
      • You can transfer money online or at the ATM (Furikomi)
      • You can sign up for direct deposit
      • Finally, you can simply wait for them to bill you. You receive a post card in the mail with a bar code, and you take that to 7-11, etc. to pay in person, or you can pay via various apps recently.

      Blurred Lines

      Importantly, not all of these payment methods can be used at all shops. At the same time, many are spanning the boundaries and blurring the lines.

      Some examples include:

      • Both Bandle and Air Wallet support issuing a physical prepaid card.
      • au Pay and au Wallet are tied together, and au Supports charging mobile Suica directly from the au Pay app as well.
      • SMBC Visa Prepaid and Kazoku-no-saifu cards both support physical ID credit cards, as well as Apple/Google wallet – but while the physical card supports Visa Touch, the mobile wallet supports the competing iD contactless protocol instead.
      • Mercari supports MerPay, which lets you use your balance to pay for things via QR code, you can also use your balance for Mercari shopping, and also register it on your phone to pay via iD contactless payments.

      The point is mainly that payment methods are quite varied in Japan, and there are a lot of choices in general – but there is one thing we don’t see too often: Deposit type credit cards.

      Deposit Type Cards

      Deposit Type Credit Cards, which exist somewhere between normal (post paid) credit cards, allow you to have a credit card that is based not so much on your credit score, but on how much of your money (the deposit) the issuer holds.

      These types of cards are useful for a few situations:

      1. They can typically be issued to almost anyone, even if they don’t have much of a credit record. Provided you don’t have a record of fraud, etc., you can probably pass the credit check even if you a freelancer, or don’t have steady employment.
      2. Foreigners without strong connections to Japan are often denied credit. This is because they could run up a large bill and then flee the country. With deposit-type cards, the issuing company holds your deposit, so they are more willing to issue cards to foreigners.
      3. Debit cards and prepaid credit cards typically don’t build up your credit record, whereas deposit-type cards do. Even though the issuer holds your deposit, you technically do borrow money from them – and so they report your status to CIC or another Japanese credit union. This means they can be used to help you build credit.
      4. If you want to avoid credit card debt, and also avoid keeping cash around, but the company you are dealing with won’t accept prepaid credit cards, then a deposit-type card is a good answer. For example, au Supports direct bank withdrawals and credit cards for phone and internet bill payments, but they don’t support debit cards or prepaid cards like Kyash. They do support deposit type cards, though, since those show up as “normal” credit cards.
      5. Like a debit card or prepaid card, you can only spent that has been added to the account – which limits accidental overspending.

      Differences Between Prepaid vs. Deposit-Type

      With a prepaid credit card, you load money onto a card, and then you spend that money, which is usually deducted in close to real-time. Prepaid cards are loaded with funds, and they carry a positive balance which decreases as you make purchases. If you try to make a purchase which is larger than your balance, the transaction will be declined.

      Since prepaid cards operate in near real time and you spend from your existing balance, there is no “bill” that comes. When your balance runs low, you can charge your card via some method such as cash at the ATM – some even allow automatic charging from your bank account, etc.

      With a deposit-type card, you must send the issuer a cash deposit either before or immediately after opening the account. Once they receive and record the deposit, they will enable the card for use.

      As you use the deposit-type card, your balance due grows. If you made 5000 yen worth of purchases during the month, then you will owe the issuer 5000 yen. Just like with a normal credit card, they calculate the amount due after the end of the billing cycle, send you a bill, and usually automatically deduct the payment from your bank account in the following month.

      The point here is that your deposit (typically, 30,000 yen to 50,000 yen or more) isn’t touched. That doesn’t become your card balance, and the deposit doesn’t decrease as you use the card. The deposit is essentially money they are keeping “just in case” you decide not to pay – but they don’t actually use it under normal circumstances.

      Instead, they tally up your purchases, calculate how much you owe, and bill you just like any other credit card would. The only difference is that your “credit limit” is defined by your deposit. If you have 30,000 on deposit and you spend 5,000 , then you have only 25,000 remaining on your credit limit. Once you pay back then 5,000 yen, then that portion of your credit limit is restored, and you can spend up to 30,000 JPY again.

      In practice, the amount you can spend is defined by your deposit, but the payment for your purchases doesn’t come from your deposit.

      Use of Deposit

      The only time your deposit is ever used would be if you refuse to pay your bill. In that case, they would just take the amount you owe from your deposit.

      If you ever cancel your account, then you will get your deposit back – though it often takes a few months.

      Revisiting Reasons

      So as mentioned above, there are really two main reasons you might need one of these cards:

      1. You find it difficult to get a normal credit card and want to build credit.
      2. You ideally want to use prepaid cards for payment, but some companies won’t accept them.

      The first category seems relatively self explanatory. Even in the age of PayPay and Mobile Suica, many online purchases require a credit card. You could use a Debit card or Prepaid card, but they won’t help you build credit. Also, not all vendors accept them, which leads us to the second reason…

      Not all companies will accept Debit cards or Prepaid cards. Gasoline stands and Hotels are notorious for this, but for example au Mobile Phone/Home Internet payments also don’t accept prepaid cards. Google’s domain registration service also won’t accept them.

      Prepaid Refusal Reasons

      Why do some businesses refuse prepaid cards? There are two main reasons:

      1. The final amount might not be known at the time of initial use
      2. You might not fund the account in the future

      For example, if you give your credit card to a hotel, they don’t know how much room service you will be eating, how many pay per view movies you will watch, etc.

      They might figure that you could reasonably spend up to 20,000 in addition to the 10,000 basic cost of the room. In this case, they would put a temporary “hold” of 30,000 on the card. This lets the credit card company know to consider that amount spent temporarily and reduce your credit limit by that amount.

      Many prepaid cards don’t implement this type of temporary hold, and so some companies just block all prepaid card issuers even though some cards (Like Kyash) do implement this feature now!

      For recurring payments including such as phone, electricity, etc., they are often billed after the fact, and with a prepaid card (or a debit card) there is always a possibility that you will simply not fund the account. If there is no money in the account, they can’t make the charge.

      This is a bit silly, since you could also simply cancel your credit card. Also, many companies allow payment via direct debit, which also depends on there being money in your account.

      Merchant can’t guarantee sufficient funds at next billing cycle with a prepaid card. This is technically true with credit cards too, as there may not be sufficient credit limit remaining – but this is a much less common problem.

      Also, prepaid credit cards (“Shopping” cards) are a relatively new phenomenon in Japan, and they did not have recurring payment support until very recently. Hence, many vendors just block all prepaid cards based on outdated data.

      How Deposit-Type Cards can help

      If a vendor blocks prepaid cards and debit cards, but you still want to limit how much they can pull from your card, a deposit backed card can help you. You know that no matter what, the card issuer won’t accept an amount larger than your deposit, so if you only have 30,000 on the card, you aren’t going to be charged more than that based on some billing mistake or credit card fraud.

      If you don’t want to leave cash lying around in your bank account for direct debit, likewise, you can use a deposit-type card, and simply pay the monthly bill as part of your budgeting process. It’s easy to forget what bills have not been debited yet, and potentially spend money that will be needed for a bill payment – especially if you don’t know the exact amount – but with a deposit-type card, you will know the exact amount of your next bill payment amount ahead of time and can plan for it.

      Popular Deposit Type Cards

      We’ll cover more details on each of these in a future post.

    4. Should I pay down debt first, or start investing now?

      The Rule

      There are three components of any investment:

      1. The Risk
      2. The Expected (or average) Return
      3. The Taxability

      You often hear about “Risk vs. Return”, but the actual return you get is of course affected by taxes.

      Investments

      When you make an investment, you are taking some amount of risk (at least in the short term) with the expectation that you will make gains.

      For example:

      1. You could put your money into a savings account at around 0.33% that’s practically nothing, but the risk is very low. Even if the bank failed, the government would step in and make things right. The main long “term” risk is that interest rates might get even lower.
      2. You could put your money in something like the S&P 500. Here the expected returns are much higher (based on historical data), but short term returns are quite variable. You could easily have a large loss in your first year of investing. Your overall effective risk lowers as time goes on, but it doesn’t reach a theoretical zero chance of losing money until you get to around 20 years. What’s more, if you are investing in US Dollar based securities from Japan, you also have exchange rate risk. Still, you can expect an overal average of something like 7% after taxes.
      3. If you invest in the stock market in Japan, you might be able to expect something like 3-4% dividend income from high dividend stocks, which would be a bit less after taxes.

      The point here is, you have a range of options, but the higher of a return you want to chase, the less certainty you will have.

      Debts

      The same is true from the bank’s point of view. If they lend money for a mortgage, it’s relatively low risk since they could always sell the house. If they lend you money via a credit card loan, well that’s high risk since you might decide not to pay it back.

      From the bank’s point of view, they should charge more when loaning money to riskier borrows, and they should charge less when the loans are secured.

      Sadly, though, from your point of view, your bank loan is “risk free” in the sense that there is pretty much zero chance that the bank will say “Oh you don’t have to pay as much this month”.

      They may count your loan as risky because they don’t know 100% if you will have the will and ability to pay – but your obligation is to pay in full, on time, every month, like clockwork.

      What this means is that if you have a credit card balance at 12%, a student loan at 6%, a housing loan at 1%, and a shopping loan at 1% – they are all “risk free” because you know how much you will owe, and when. The only real risk is that the interest rate might change.

      Debts as Investments

      You can think of debts as investments with negative returns. Your 6% student loan is an “investment” which returns -6%, risk free.

      Paying down your debt, then, is reducing the balance of your -6% investment, and when compared to your current situation, is almost the same*1 as investing in a risk free product at 6%.

      This is because paying down 10,000 yen of this 6% loan has almost the same effect as investing in an offsetting financial product that earns 6% risk free.

      Example:

      For the sake of simplicity, let’s say interest is calculated on your average balance, charged or paid at the end of the year, and compounded yearly. We’ll also assume a world with no taxes.

      For every 10,000 yen of your loan, you will owe 600 yen at the end of the year.

      For every 10,000 yen you invest, you will make 600 yen at the end of the year.

      Scenario 1:

      You owe 20,000 yen, so you end up owing 1,200 yen.

      Cash Flow : -1,200 yen

      Scenario 2:

      You owe 20,000 yen, so you end up owing 1,200 yen.

      You invest 10,000 yen, so you end up making 600 yen.

      Cash Flow: -600 yen

      Scenario 3:

      You owed 20,000 yen, but you paid down 10,000 yen at the end of last year, so now you only owe 10,000 yen.

      Cash flow: -600 yen

      Summary

      You can see here that the end result of paying down your loan by 10,000 yen is the same as keeping your 20,000 yen loan and investing 10,000.

      Where things go wrong: Risk & Taxes

      Many people understand this to some extent and say “Well investing can make sense when when I have debt, so long as the investing returns are higher than the interest rate on my loans!” In effect, they ask themselves “Why should I pay down my 3% student loan when I could invest that money in the stock market where I could get 10%?”

      Fair though, but there are two problems:

      Risk – As mentioned above, the debts you owe are effectively risk free, except for interest rates in many cases. Paying them down is in effect investing risk free. So, the choice between paying down your student loan debts or investing in the stock market isn’t a simple 3% vs 10% question, it’s a question of which is better: 3% risk free vs. 10% with high risk.

      Taxes – In the example above, we ignored taxes, but leaving aside mortgages and business loans, interest on most consumer loans is not tax deductible. Investment income, on the other hand usually does have taxes taken out. Assuming you are investing in a NISA account, you may be able to avoid this up to certain limits. Nevertheless, if you are comparing paying down a 3% debt vs a 10% pre-tax investment return, the real choice may be between a 3% risk free investment vs. a high risk investment with a 6-7% post tax expected return.

      Comparison with other risk free investment alternatives

      Normally, you might have the following choices for risk free investments.

      1. Bank Accounts – Less than 0.5% return
      2. Term Deposits (1 year term) – <=1% return
      3. Japanese Government Bill (1 year term) < 1.5% return
      4. Japanese Government Bonds (10 year term) < 3% return

      All of these returns are nominal pre-tax numbers.

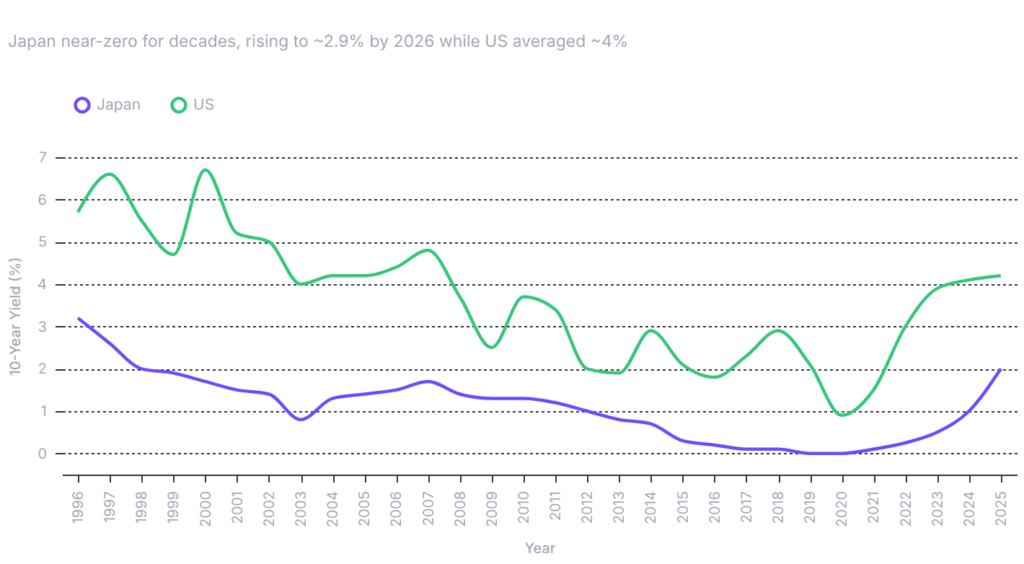
      As of the time of this writing, even if you buy a 10 year government bond, you will only get a 2.785% return. This is the highest it’s been in over 10 years, but still quite small compared to most consumer debt.

      So if you pay off a 3% student loan, you can get a better effective return than you can get even by investing in 10 year government bonds.

      Not only that, but if you have credit cards, of other consumer debt, chances are you owe 6%-14% APR.

      This means your choice comes down to “investing” in paying off a 6%-14% loan, tax free and risk free, or trying to make that much risk free which is … completely impossible.

      The Bottom Line

      For any loan with an APR above about 4%, paying down the loan instead of investing in a risk laden financial product that will likely return less after taxes is the obvious choice.

      *1 I say “almost”, because there may be differences in compounding periods, methods, interest rate adjustment timing, etc.

      Mortgages

      The situation with Mortgages is a bit murky. With the average home loan interest rates still under 1%*3, and the fat that home loan interest is generally tax deductible, things are a bit less clear cut than the consumer debt examples above.

      The expansion of the Shin NISA program which enables tax free investment opportunities for amounts on par with some home loans swings things even farther towards the investing side.

      For example: Paying down a 1% home loan may save you less than that 1% since it was tax deductible. At the same time, if you were lucky enough to get an average of 8% in an index fund in your NISA no taxes need be paid on that gain.*2

      This means you might be weighing a 0.7% risk free return vs. a risky 8% return. Here, the risk vs. return trade-off seems very reasonable.

      Still, if you suddenly lost your job during an economic downturn while the stock market is in a bust cycle you may well wish that you had paid off your mortgage before investing in risky assets.

      The main point is this: Investing in stocks, gold, bonds, etc. is really not defensible if you owe any kind of consumer debt such as credit cards, etc. Mortgages are typically much lower interest rates and tax deductible, so considering your options is a sane thing to do.

      *2 In Japan, at least. Some funds pay taxes overseas first before distribution.

      *3 My choice of words here is intentional. Property investment loans tend to be well above 1%, currently hovering around 2.5%.

      The Exception

      If your place of work has a 401k (or other DC plan) with matching contributions, then for every 10,000 yen you invest, you might be getting an additional 10,000 yen from your employer. Add this to the tax deferment feature, and suddenly you might be able to get 20,000 per month added to your DC account while your paycheck is only dropping 6,000-7,000 yen. That means an immediate and roughly a 300% return for the amount you invest each month.

      I would invest in any account with matching to the maximum allowed before paying off low interest loans, assuming my cash flow situation was stable.

      Bear in mind, though, that 401k accounts in Japan can not be withdrawn from, borrowed against, or liquidated except in exceptional circumstances. I would be ironic if you were missing credit card payments while you had millions of yen in the bank that you couldn’t touch.